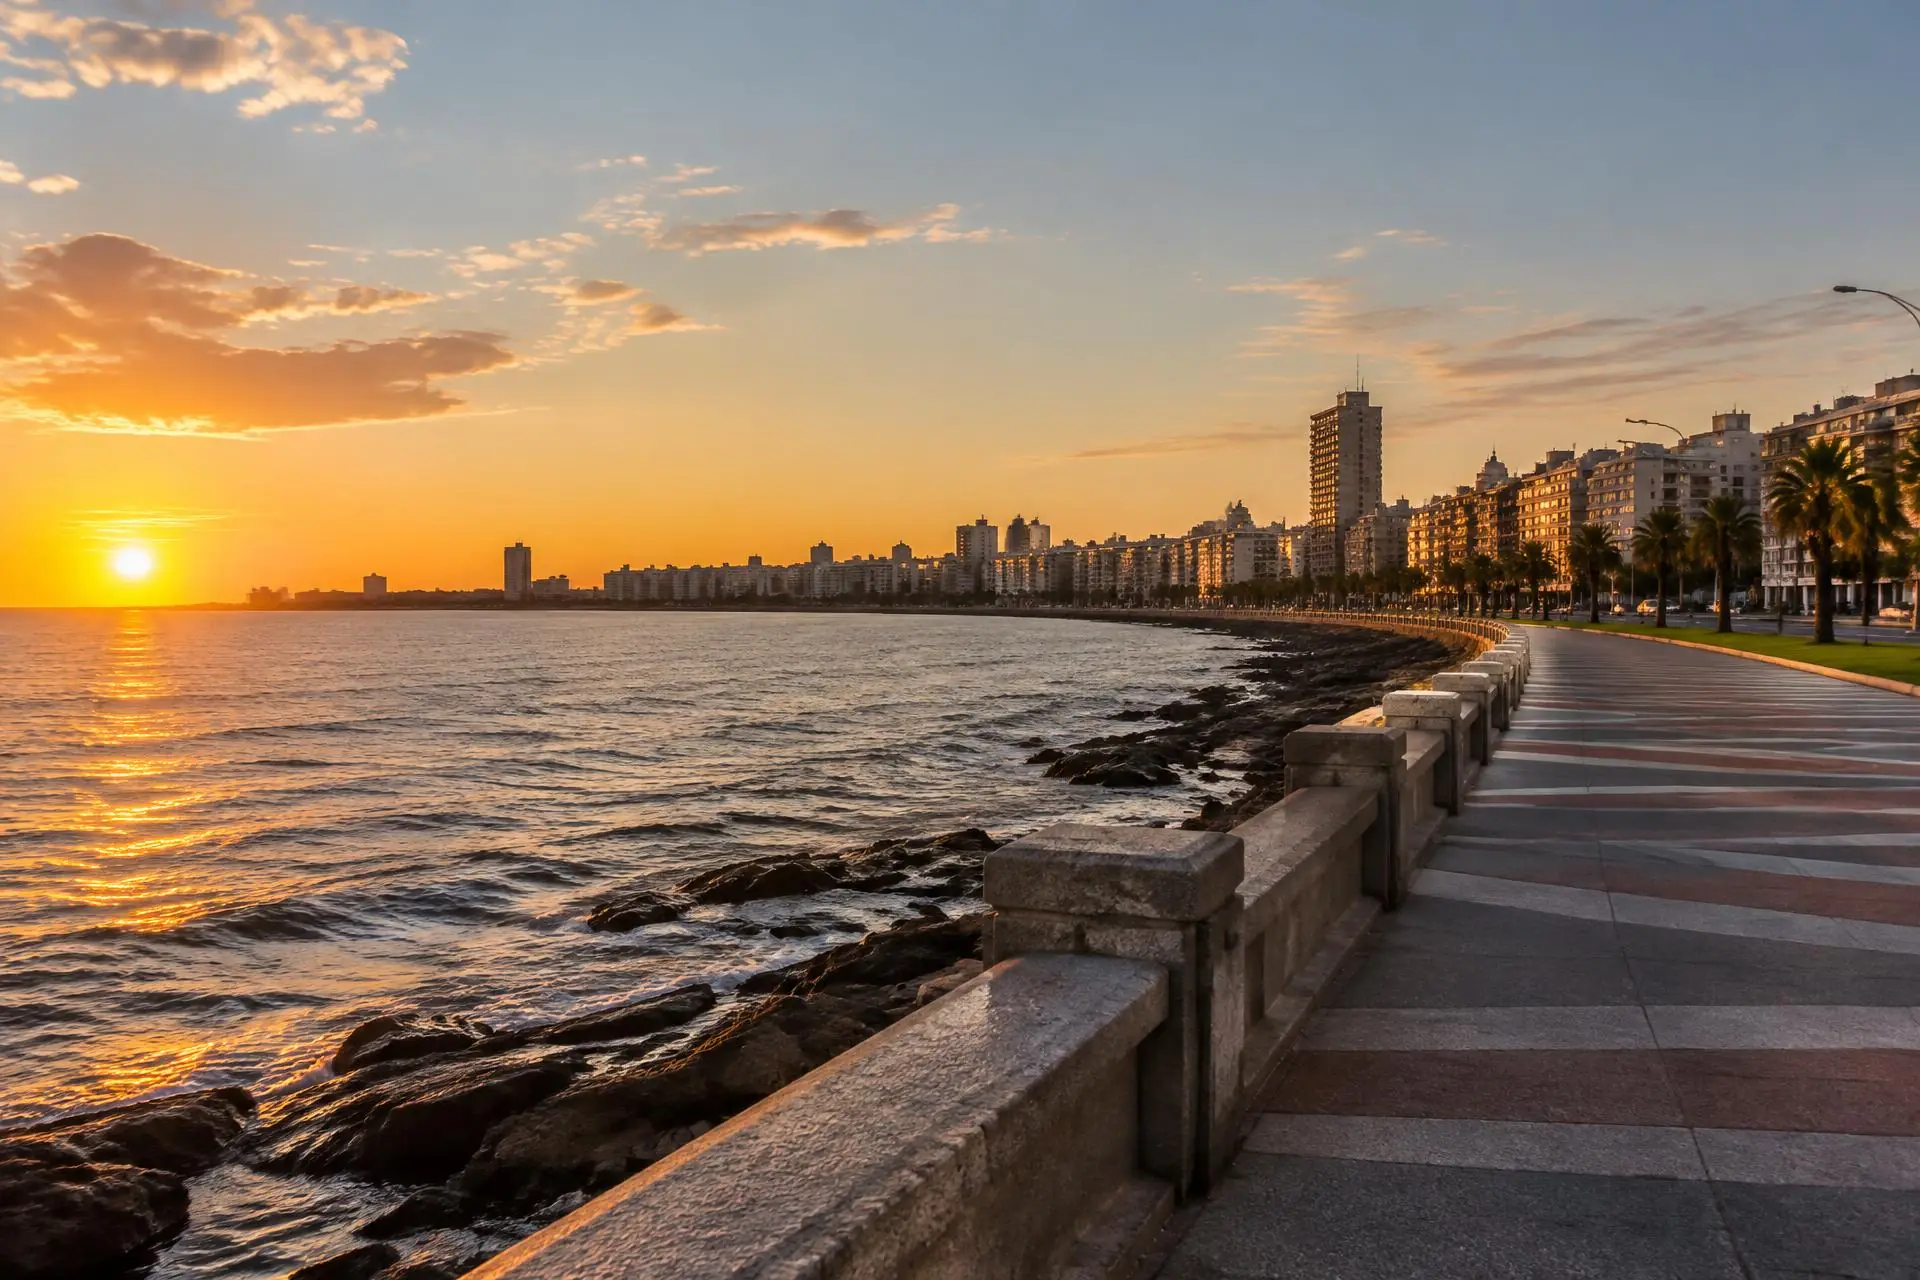
Residency · Americas
 Residency · Americas
Uruguay Tax Residence by Investment
Tax residence in Uruguay without 183 days of presence, through real estate above 3.5 million indexed units with 60 days a year in the country, or larger property or business investments. It is separate from legal residence.
- Investment from
- See the costs
- Processing
- To confirm
- Family
- See the family rules
- Stay required
- 60 days a year
Decision summary
- What do you obtain?
- Uruguay Tax Residence by InvestmentRoute to citizenshipTax residence does not lead to citizenship by itself;
- What does your family invest?
- Real estate above 3.5 million indexed units (about USD 583,000) with 60 days a year, or larger property and business routes.
Full wordingHide full wording
Real estate above 3.5 million indexed units (about USD 583,000 in November 2026) with 60 days a year in Uruguay; real estate above 15 million indexed units; or a business investment above 15 million indexed units creating 15 jobs.Full details below - What is additional?
- Indexed-unit amounts move with inflation; the USD equivalent uses official values for November 2026.
- How long does it take?
- Information pending verification
- Must you travel or live there?
- At least 60 days a year in Uruguay for the 3.5 million indexed-unit real estate route, with ownership on 31 December.
- What is the main drawback?
- From 1 January 2026, the 3.5 million indexed-unit route alone does not qualify for the tax holiday on foreign passive income.
- Family inclusion
- Information pending verification
- Program status
- Operational
Overview
Tax residence is decided by the tax authority (DGI), separately from legal residence. It does not by itself give the right to live in Uruguay, and legal residence does not by itself make someone tax resident.
Without 183 days of presence, one route is real estate above 3.5 million indexed units (about USD 583,000 in November 2026) with at least 60 days a year in Uruguay and ownership on 31 December. Others are real estate above 15 million indexed units, or a business investment above 15 million indexed units creating 15 new jobs.
New tax residents may opt for a temporary exemption on foreign passive income. Under Law 20,446, people becoming tax residents from 1 January 2026 qualify only with real estate above 12.5 million indexed units or annual project funding of 625,000 indexed units, unless they meet the main presence test, so the 3.5 million route alone does not qualify.
Path to citizenship
Does not lead to citizenship
Tax residence does not lead to citizenship by itself; citizenship follows legal residence (three years with a family established in Uruguay, or five without).
See every residency route to citizenship →Who this program may not suit
Taken from the facts recorded on this page. It may not suit you if:
- You cannot meet the stay rule: At least 60 days a year in Uruguay for the 3.5 million indexed-unit real estate route, with ownership on 31 December.
Investment pathways
- Investment pathway
- Tax residence decided by the tax authority (DGI) through presence, real estate or business investment; separate from legal residence.
- Minimum investment
- Real estate above 3.5 million indexed units (about USD 583,000 in November 2026) with 60 days a year in Uruguay; real estate above 15 million indexed units; or a business investment above 15 million indexed units creating 15 jobs.
Checked against official programme sources
Application process
The government has not yet published an application process for this programme.
Investment and fees
Qualifying investment amounts and government fees are always shown separately. We do not publish single "total price" figures, as the total depends on family composition and circumstances.
- Estimated additional costs
- Indexed-unit amounts move with inflation; the USD equivalent uses official values for November 2026.
- To be confirmed
- Government fees · Due diligence fees · Investment holding period
Checked against official programme sources
Residence requirements
- Residence requirements
- At least 60 days a year in Uruguay for the 3.5 million indexed-unit real estate route, with ownership on 31 December.
- Potential route to citizenship
- Tax residence does not lead to citizenship by itself; citizenship follows legal residence (three years with a family established in Uruguay, or five without).
- To be confirmed
- Renewal requirements
Checked against official programme sources
Due diligence and documentation
Applicants and included dependants undergo background and source-of-funds checks by the relevant authority. Documentation requirements are confirmed during preparation — no documents are needed for an initial consultation.
Considerations, limitations and risks
Important restrictions
From 1 January 2026, the 3.5 million indexed-unit route alone does not qualify for the tax holiday on foreign passive income.
- Published thresholds are not comprehensive costs; taxes, professional fees and dependant charges may apply.
- Immigration law, visa access and naturalisation rules can change without notice.
- Individual eligibility depends on nationality, financial background, due diligence and program-specific criteria.
Status and authority
- Operational status
- Operational
- Official government authority
- Dirección General Impositiva, Uruguay
- To be confirmed
- Legal basis · Nationality restrictions
Programme rules change; your advisor confirms every figure before you commit.
Frequently asked questions
Is tax residence the same as legal residence in Uruguay?
No. Legal residence is granted by the National Migration Directorate and needs no investment. Tax residence is decided by the tax authority and can be reached through presence or investment.
Does the 3.5 million indexed-unit property route give the tax holiday?
Not on its own for people becoming tax residents from 1 January 2026: they need real estate above 12.5 million indexed units or annual project funding of 625,000 indexed units, unless they meet the main presence test.
What is the minimum investment for Uruguay Tax Residence by Investment?
Real estate above 3.5 million indexed units (about USD 583,000 in November 2026) with 60 days a year in Uruguay; real estate above 15 million indexed units; or a business investment above 15 million indexed units creating 15 jobs.
Can my family be included?
Family inclusion rules vary and will be confirmed for your circumstances.
Is there a minimum stay requirement for Uruguay Tax Residence by Investment?
At least 60 days a year in Uruguay for the 3.5 million indexed-unit real estate route, with ownership on 31 December.
How long does the process take?
Timeframes depend on the authority and the completeness of your application. An advisor can provide current guidance.
Does the Uruguay Tax Residence by Investment lead to citizenship?
Tax residence does not lead to citizenship by itself; citizenship follows legal residence (three years with a family established in Uruguay, or five without).
Is approval guaranteed?
No. Every application is decided by the government concerned after due diligence, and requirements can change.
Discuss Uruguay with an advisor.
Share your objectives in confidence. An advisor will outline the options that may be relevant to your family and circumstances.